Tag: finance

  • Living with Your Parents: The New Normal

    Living with Your Parents: The New Normal

    Go to school. Graduate. Get a job. Move out. Build your life. This straightforward trajectory feels increasingly like the life path of yesteryear. More and more young people are remaining in the nest and living with their parents despite having graduated. On one hand, a weaker economy and bleaker career prospects have played a part. However, there are other factors to consider when looking at this phenomenon.

    In 2011, approximately four out of every ten Canadians in their twenties lived with their parents. This is a noticeable increase from 27 percent thirty years prior. Employment and incomes have been definite factors in this change. These two influences peaked around the 1960s and 1970s and have been in downward trajectories since then. The labour market has provided much greater success for women since the 1960s, and their growing prominence in the workforce has also had an impact.

    Economics is not the only facet of this situation. Major cultural shifts include people choosing to marry at a later age. Most young adults lived with a romantic partner from the late nineteenth century onwards. This has slowly changed throughout the last several decades. Marriage allows for a multi-income household, and without that support, it is no surprise that more and more young adults choose to live at home with their family instead. Metropolitan areas have become increasingly populated as the preferred living location. The choice to remain in these cities has the repercussion of dealing with a higher cost of living. 42 percent of twenty-somethings lived at home in 2011, whereas that number for Torontonians was 57 percent.

    Multigenerational living arrangements are becoming more prevalent across Canada. Young adults belonging to a visible minority group or whose parents migrated to Canada were more likely to live at home in 2011. Certain cultures have different viewpoints on when children are expected to leave home. For many, it is common for parents and their offspring to cohabitate. As Canada’s multiculturalism continues to grow and flourish, it is not surprising that this practice is carried out here. Young adults can reap the financial advantages of this, while also gaining emotional support by not having to live alone. The older generation also does not have to live alone and have the practical support of their children to help them with household matters. As the population in general continues to age, it is not uncommon for younger people to support their older parents as much as they possibly can.

    The stigma of living with one’s parents is slowly but surely changing. As rent and housing prices continue to skyrocket, it is practical to withhold from plunging into those expenses. The transition from finishing school to securing independence is being seen as a more fluid journey, as opposed to the simpler steps that it once entailed decades ago. Young adults may not have the immediate job opportunities or easy entry into the housing market that their parents had. However, they do have the support of those parents and greater freedom in exploring different career paths and entrepreneurial endeavours.

    Go to school. Graduate. Go back to school. Work. Move out. Quit. Move back home. Start your own company. The steps to adulthood are blurrier and more winding than they were before. While there are tougher circumstances in regards to employment and the economy, there are also life choices, cultural shifts, and a changing world to consider. Independence and adulthood are less straightforward than they once were, but young adults also have opportunities unlike ever before.

    Sources:

    Fry, Richard. “For First Time in Modern Era, Living With Parents Edges Out Other Living Arrangements for 18- to 34-Year-Olds.” PewResearch Center. http://www.pewsocialtrends.org/2016/05/24/for-first-time-in-modern-era-living-with-parents-edges-out-other-living-arrangements-for-18-to-34-year-olds/

    Milan, Anne. “Diversity of young adults living with their parents.” Statistics Canada. http://www.statcan.gc.ca/pub/75-006-x/2016001/article/14639-eng.htm
  • How to Save Money to Pay for College or University

    How to Save Money to Pay for College or University

    When you start thinking about attending college or university, it can seem like an expensive task. Tuition, books, and residence fees add up to a pretty hefty price tag, but that doesn’t mean it’s impossible. There’s a lot you can do when you’re still in high school to save money toward paying for college or university.

    Start Saving as Early as You Can
    The sooner you start saving money for school, the better. The best way to do this is to open a separate savings account at your bank, where you can deposit money you want to save for school. This way, your money will also earn some interest for you.
    You should also work out a budget of what it will cost to attend the college or university program of your choice. Schools and programs will vary in cost, but by looking at a wide variety of schools you will have an average price range to use as your savings goal.
    Once you know your goal amount, make sure you put money into your savings account as often as you can. A little bit at a time is all you need, such as money from your allowance or birthday and holiday gifts. You’ll see – it will add up pretty quickly.

    Earn Money Working Part-Time or During Summer
    Many students have part time jobs in high school. If you’re already working, then you can easily save money by putting some money into your savings account immediately after each paycheque. By doing this first thing each payday, you can make sure you save before you spend it.
    However, not every student has the opportunity to work during the school year, whether due to family obligations, sports and clubs, or parents who prefer you focus on academics. The thing to remember is that there are always breaks, such as spring break and summer vacation, which are an ideal time to pick up some work.

    There are many flexible jobs for students, as well. These include retail, food service, babysitting, camp counsellor, yard work and snow removal, washing cars, and even dog walking, to name just a few options.

    Start a Registered Education Savings Plan
    Known as an RESP, these are specific bank investments designed to help families save money for a child’s education. These plans enable parents and other family members to contribute to pay for school, and the younger the child is when the RESP is opened, the better.
    These investments offer benefits with taxes, as well as government matching of contributions up to a specific dollar amount each year. This makes an RESP a valuable way to save for school.

    Apply for Scholarships and Grants
    While not saving money per se, scholarships and grants are a great way to offset the costs associated with college and university. There are many scholarships for whatever program you want to study. The qualification requirements will vary, meaning you will always be able to find something to apply for. Some scholarships can even be applied for as early as your third year of high school.
    Scholarships and grant opportunities can be found all over, from local businesses and organizations in your town or city, as well as province-wide and Canada-wide.

    Student Loans
    It’s not always possible to save the entire amount you will need to cover the cost of your education – and that’s okay. Student loans exist for exactly that reason: to ensure that students who want to attend college or university can do so.
    Many banks offer student loans for educational purposes, and there are also government student loan programs, such as the Ontario Student Assistance Program (OSAP). These programs are valuable resources for students to help finance their education. The terms of the loan will vary depending on the source, but often include better interest rates and different repayment options than a standard loan.

  • Long-term Financial Planning for Students

    Long-term Financial Planning for Students

    As a university or college student, you’ve likely got a lot on your mind. However, when you’re looking at your education as a bigger picture, don’t forget to factor in your finances—as tempting as it may be to (not) do so. Many students are already strapped for cash with the increasing costs of tuition and stockpiling student loans. Responsible and long-term planning may help you avoid financial emergencies in the future.

    Here are some things to consider when planning your financial future.

    A good credit history can help you down the road if you ever want to take out large loans from the bank, or make large purchases such as a car or a home. To start accumulating good credit, you can sign up for a credit card and start using it to pay for your groceries or your textbooks. If you can demonstrate to your bank that you can reliably make your monthly payments—in essence, replace the money you’ve “borrowed” from them each month with your own savings—you’re well on your way to building good credit. Of course, make sure to know your limits: never overspend on your credit card unless you can hold yourself accountable and pay back the money. A lot of people are in debt today because they take advantage of this aspect of the credit card- don’t let that e you.

    Setting up a savings account is also a smart idea, particularly if you have a part-time job or some other form of income. Each time you get paid, you can set aside a portion of that money and deposit it into your savings. Depending on the deal you’ve struck with your bank, the amount of money you have in that account may grow (probably slowly) over time. But even if you don’t accumulate growth, having some money set aside for emergencies is still a responsible thing to do. This will also ensure that when you get your paycheque, you don’t spend it all in one place!

    Finally, a long-term financial plan is something that should be in the back of your mind as you go through your education. Unfortunately, degrees and diplomas are usually very expensive. Think about how your education is going to be financed (part-time work? student loans? bursaries and scholarships?), not only currently, but in the long run. Furthermore, think about whether you are going to enter the workforce right after graduation and start paying back any borrowed money, or whether you are going to pursue further education, such as graduate or professional schools. These decisions will determine the kind of financial steps you will have to take to ensure you will be able to pay for your schooling.

  • Money Management

    Money Management

    If you are anything like me, you will often find yourself thinking, “Just one more small purchase won’t matter.” And if you’re even more like me, you will soon realize that maybe that small purchase did matter when you discover that your bank account is now empty. It would be silly to think that one small coffee made you broke, but when you figure out that maybe having one every day is a little excessive, you have the first step toward money management down: awareness.

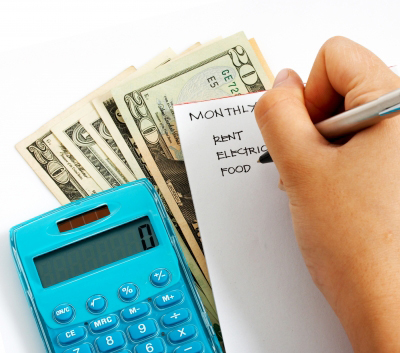
    Take stock of your funds. Figure out how much you will earn each month, and write it down. Next, find a little notebook and start keeping track of everything you buy. Write down where you bought it, on which date, and how much you spent. This serves the purpose of telling you where all the money goes. It might even serve the extra purpose of telling you that you have a caffeine addiction, and maybe you should cut back a little. Starbucks four days in a row, five dollars each time? There are twenty dollars, gone. Kind of scary, isn’t it?

    Keep that spending diary for three months so that you can get a good idea for the average you spend on each kind of purchase. Doing so will then assist you to start making changes in your lifestyle: this is where you have to start limiting yourself and have self-control.

    Trust me; I know it is not easy to break a spending habit. When you do something so often that it becomes routine, breaking that routine throws off the rest of your day. That being said, it is now time to break out a coloured pen or highlighter. Circle or highlight every habitual purchase you made in the last three months, and calculate the total cost. Then think of how many hours it took to earn that money. A little sobering, right? Once you realize that your time equals money, it becomes a lot easier to make good decisions regarding your spending.

    Now that you have figured out what you can cut back on, it is time to make a budget. Figure out the main categories your purchases fall under. For some, those might be their cell phone bill, car payments and gas, entertainment such as movies, music, and video games, going out to eat, savings, and so on. Certain bills will always remain the same, such as car payments and your cell phone bill. Some put 10% of their entire paycheque into a savings account which they do not use under any circumstances. With everything else, though, allocate a certain percentage of your remaining funds to each category.

    For example: let’s say that you make $750 per month. 10% of that is $75 which goes into your savings. Your car insurance payment costs $100, so now you have $575. Your cell phone bill costs $50, and the remainder is $525. Now you can assign a percent to everything else. You may calculate it so that you have extra money left over for emergencies or unexpected nights out. As long as you never go over your allotted limits for each category, then you won’t find yourself with an unexpectedly empty bank account again.

  • Comparing Tuition Fees in Canadian Schools

    Comparing Tuition Fees in Canadian Schools

    When children are young, their parents sometimes begin to set aside money for different purposes. Sometimes they start special bank accounts so that their sons or daughters will have some money to spend when they get a bit older. They might also start an education fund to start to save money for a university or college program in the future. Why would they do that? They know that post-high school education can be expensive, but saving money for their children can help make it possible to continue studying. When the time comes to choose a post-secondary school, students can also help by comparing costs and seeing where they can get the best value for their tuition money.

    Tuition refers to the fees students pay for being able to go to classes and to earn degrees, diplomas, or certificates. Normally, the cost of books and other supplies are not included in the tuition, which covers salaries, maintaining the buildings, and other basic costs. Tuition fees have been rising quickly almost everywhere in Canada, much faster than the cost of food, clothes, and other daily needs. In some places, the fees have almost doubled in the past five years, and in other places, they are almost four times as much as they were. One exception is the province of Newfoundland and Labrador, where tuition has been kept at the same level as it was in 2004. Ontario generally has the highest tuition fees, followed by Saskatchewan. Quebec and Newfoundland and Labrador generally have the lowest fees.

    Even within each province, tuition fees can vary a lot. In Saskatchewan, for example, there is only about a $200 difference in tuition between the most and least expensive university tuitions. In British Columbia, however, the most expensive university costs seven times as much as the lowest-priced. This difference can add up to a large amount of money for a four-year program, which could cost almost $55,000 by 2023. Unless students can live rent-free with their parents, they also have the expenses of rent, food, and other necessities of life. This can add up to a lot of money. Cost is an important factor in choosing your program after high school, but it is only one part of the decision.

    When the time comes for you to choose a post-secondary program, money should not be your only consideration. Sometimes, the best programs with the most support for job searching are also the most expensive. An expensive institution might also offer extra benefits, such as music or sports programs, volunteer opportunities, or a selection of courses not offered elsewhere. If these benefits are important to you, a high-priced school can be a good option. If not, a lower-cost program might be best. Beside these factors, being close to family or friends, being in a big city or small town, or other personal considerations should influence your decision. If you research your options well, you can find a program that combines good economic value with a useful education for your future.

  • The Dangers of Student Credit Cards

    The Dangers of Student Credit Cards

    For many young people, the temptation of their first credit card is too much to resist. That is why credit card companies will often set up booths on college and university campuses across Canada to tempt you with free gifts and low interest rates for signing up with them. While credit cards can be an excellent way to build your credit rating, the responsibility that comes with owning one cannot be overlooked.

    When I first entered college, I saw a booth on campus advertising free NHL hockey blankets for signing up. Not only that, but acceptance was virtually guaranteed. For someone fresh out of high school, a credit card makes you feel important and like an adult. Being able to use it whenever you want to buy clothes, electronics, make-up and more is a thrill. The thrill will soon wear off when you realize that you have used up most of your credit limit in only a few months and have no way to pay it off.

    Credit cards should not be taken lightly. While the company may advertise an interest rate of 1.99%, this is often only an introductory offer and the rate will skyrocket to 18% or higher after your first month. This means, on a $100 purchase, you will be paying $18 in interest directly to the credit card company. Over several months of not paying off your balance in full, this quickly adds up. Soon you will owe hundreds of dollars that you didn’t even spend!

    If you do decide to sign up for a credit card, there are several things you can do to reduce the temptation of overspending. The first, and most important, is to make sure you have the funds needed to pay off your balance before you even use your credit card. Paying off your balance in full each month is an excellent way to build a credit rating, as you are showing the bank that you are responsible and have a steady income. The second is to leave your credit card at home and do not carry it with you in your wallet. This tactic helps to eliminate the temptation of overspending and using the card for purchases you do not need.

    Of course, there is always online shopping. Online shopping should only be done when absolutely necessary (for Christmas gifts, for example). It is also advisable to get a credit card with a low credit limit – $1000 should be your absolute maximum. Anything higher and you run the risk of using it frivolously.

    Credit cards can be an excellent tool for building your credit rating and establishing yourself, if used responsibly. If you decide to sign up for a credit card, ensure you take the steps outlined above to reduce overspending and, ultimately, reduce your stress level. After all, who needs extra stress during exams?

  • November Scholarships – Apply Now!

    November Scholarships – Apply Now!

    It’s November, so we know what you’re thinking about – getting through exams and counting down the days to when you will be on holidays come December. If you’re planning on starting post-secondary education next fall, thinking about scholarships is something you need to pencil in, too! Many scholarships are accepting applications NOW. Get yours in while everyone else is concentrating on Christmas vacation and you’ll have an even better shot at scoring that free money!

    1. Canadian Society for the Study of Religion Undergraduate Student Essay Contest – Open to all students enrolled in an undergraduate program at any school. Amount: $250. Deadline: April 18, 2014.

    2. Burger King Scholars Awards – Open to all students across Canada who are employed by Burger King or who are children of Burger King employees. Amount: Up to $50,000. Deadline: January 10, 2014.

    3. Terry Fox Humanitarian Award – Open to all students across Canada who demonstrate voluntary humanitarian work. Amount: $7000. Deadline: February 1, 2014.

    4. Dalton Camp Award – Open to all students across Canada. Amount: $10,000. Deadline: November 15, 2013.

    5. TD Scholarships for Community Leadership – Open to all students across Canada. 20 awards available! Amount: Up to $70,000 over 4 years. Deadline: December 6, 2013.

    6. RBC Students Leading Change Scholarship for Undergraduates – Open to all students across Canada entering post-secondary education on 2014. Amount: Varies. Deadline: Applications available November 1, 2013 – deadline TBD.

    7. Horatio Alger Canada Scholarship Program – Open to students in Quebec, Ontario, BC or Alberta. Amount: $5000. Deadline: December 1, 2013.

  • Tips for Scoring a Scholarship

    Tips for Scoring a Scholarship

    Let’s get real. Post-secondary education is expensive and very few people have thousands of dollars casually lying around the house. Most of us are in search of cash — the type that you don’t have to pay back. In other words, we’re all searching for those illustrious scholarships. If you’re new at this whole “applying-for-scholarships-because-I-need-money-to-pay-for-school-which-suddenly-isn’t-free-anymore” thing, then you’ve come to the right place.

    Here are seven helpful tips that could help you score some extra cash!

    1. You do not get scholarships for simply existing. Almost every scholarship application that you come across is going to inquire about your extracurricular activities and community involvement. You need to do something, be a part of something, or participate in something. You don’t necessarily need to be the three-time reigning champion of every competition you compete in, or the newly-elected President for every fancy club that you’re a part of. You simply need to get out there and participate.

    2. One of the hardest parts of getting free money is finding free money. Luckily, there are people who dedicate themselves to doing it for you! Make sure to check out websites like Scholarship Canada. They have information on hundreds of scholarships— both large and small. Also, take a glance at your school’s website. The majority of Guidance Councillors will actually post a list of scholarships that they’ve come across. But don’t stop there. Go the extra mile and go digging through the websites of other schools. You’re guaranteed to come across a fresh new list filled with new opportunities.

    3. Keep your eye out for obscure scholarships offered by smaller organizations. This may require an advanced Google search and some serious digging but this very well might be the key to your first scholarship. Most students set their targets on big scholarships offered by well-known companies. There’s no harm in applying for those, but your chances quickly diminish when you’re facing so much competition. However, with the lesser-known scholarships that might be sitting on page 17 of a Google search, your chances of standing out in the significantly smaller crowd are far higher.

    4. Your best bet to scoring a scholarship is to apply to as many as possible. This may sound frighteningly obvious but you would be surprised by how many people lay all of their eggs in one basket. Yes, it’s time-consuming and painstakingly tedious but you need to apply, apply, and apply some more!

    5. If a scholarship application sounds too long, too boring, or too overwhelming, there’s a pretty good chance that other students are going to think the same thing and avoid it all together. This, of course, means that you should go ahead and do it! The more tedious the application is, the less competition you’re going to have. So suck it up and get writing!

    6. Never lie. Don’t lie about your qualifications, achievements, activities, awards, or anything of the sort. Just don’t! If you get caught, you’ll suffer from third-degree embarrassment and, even worse, you may sever some really important connections.

    7. Most organizations will release profiles of the previous year’s winner. Take a look at those to find out what kind of people they’re looking for. This might give you some ideas on what to include in your own application.

  • Scholarships for Aboriginal Canadians

    Scholarships for Aboriginal Canadians

    Bursaries and Scholarships
    The Aboriginal Financial Officers Association of Canada is dedicated to helping Aboriginals reach the highest standard of excellence in finance and management. AFOA’s initiatives in the development of Awards and Scholarships are examples of that commitment.

    See link below for scholarships and bursaries.
    http://www.metisnation.org/programs/education–training/education/bursaries–scholarships

  • July Scholarships of the Month – Apply Now!

    July Scholarships of the Month – Apply Now!

    Just because it’s the summer doesn’t mean that scholarship applications should stop. In fact, there are plenty of scholarships just waiting for you to apply! Did you know that many scholarships go unclaimed? According to Canadian Living, of the $70 million available in scholarships each year in Canada, about $7 million goes unclaimed because students don’t realize so many scholarships exist. So what are you waiting for? Get applying and get that free money!

    1. SecureReset Fall 2013 Scholarship – Open to students attending any school for any program who demonstrate community involvement and academic achievement. Amount: $300. Deadline: November 1, 2013.

    2. Simplycast Ritchie Scholarship 2013 – Open to students attending any school for any program who demonstrate community involvement and academic achievement. Amount: $450. Deadline: September 1, 2013.

    3. CrossLites Essay Contest – Open to all students who reflect on one of Dr. Parker’s inspirational quotes and how it relates to their life in a brief essay. Amount: $2000. Deadline: December 15, 2013.

    4. Super Powers Scholarship – Open to students attending any school for any program who write a brief essay on what super power they would like to have and what they would do with it. Amount: $250. Deadline: September 30, 2013.

    5. 2013 Johnson Scholarship Program – Open to children and grandchildren of Johnson Affinity group members and/or Home-Auto clients. Amount: $1000. Deadline: September 15, 2013.

    6. Heroes of Our Time Scholarships – Open to all First Nations students who have completed at least one year of post-secondary education. Amount: $2000 (8 in total). Deadline: July 21, 2013.

    7. Jeremy Dias Scholarship – The Jeremy Dias Scholarship seeks to recognize a youth that has taken initiative in addressing discrimination in their school or community. Amount: Not specified. Deadline: August 15, 2013.

    8. Out on Bay Street Scholarship – Open to all students who show an involvement in the LGBTQ community. Amount: $2500. Deadline: July 31, 2013.

    9. Tronia Systems Scholarship – Open to all students enrolled in Agribusiness or related field. Amount: $1000. Deadline: October 7, 2013.

    10. Atlas Shrugged Essay Contest – Open to all students. Amount: 1st prize at $10,000; 2nd prizes at $2,000; 3rd prizes at $1,000; Finalist prizes at $100; Semi-finalist prizes at $50. Deadline: September 17, 2013.